In short:
- The territoriality principle means Uruguay taxes Uruguayan-source income: activities carried out, assets located and rights used in the country, regardless of the earner’s nationality or residence.
- Uruguay does not tax worldwide income. The main exception: tax residents pay IRPF on certain foreign investment income, widened in 2026.
- What defines the source of employment income is where the work is done: remote work performed from Uruguay is Uruguayan-source; foreign pensions and work done abroad are not.
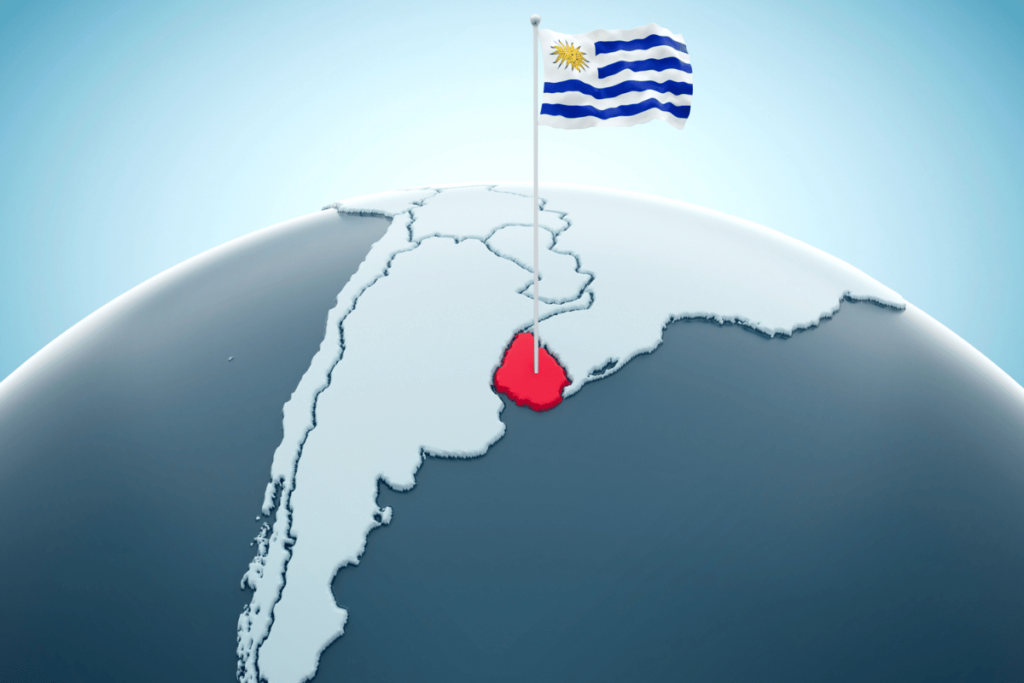
Uruguay’s tax system rests on a rule that sets it apart from most OECD countries: territoriality. Understanding it, and its exceptions, is the starting point for planning a move or an international structure. This guide explains the territoriality principle in Uruguay, what counts as Uruguayan-source income, how it differs from worldwide taxation and which exceptions apply today.
What is the territoriality principle?
It is the rule by which a country taxes income based on where it is generated, not where the earner lives. In Uruguay, the income taxes (IRAE for companies, IRPF for resident individuals and IRNR for non-residents) generally apply to Uruguayan-source income.
What is Uruguayan-source income?
- A salary for work physically performed in Uruguay, including remote work for a foreign employer (DGI ruling 6639 of 2024).
- Rent from property located in Uruguay.
- Interest on a deposit in a Uruguayan bank.
- Dividends from a Uruguayan company.
By contrast, work performed abroad and pensions paid from abroad are foreign-source.
Territorial vs. worldwide taxation
|
Territorial (Uruguay) |
Worldwide (US, Spain, Brazil, Argentina) |
| What is taxed |
Income generated in the country, with specific exceptions |
All of a resident’s income, wherever earned |
| Work performed abroad |
Not taxed |
Taxed |
| Foreign investment income |
Partly taxed (see exceptions) |
Taxed |
Exceptions to territoriality
- Foreign investment income of tax residents: since 2011 foreign dividends and interest are subject to IRPF; since 2026 (Law 20.446) also foreign rents, capital gains on foreign assets and income through non-resident entities. The general rate is 12%. See does Uruguay tax foreign income?
- New-resident exemption: during the tax holiday that income is exempt. See the tax holiday.
- Certain services provided from abroad to Uruguayan taxpayers can be treated as Uruguayan-source.
- Companies: corporate income tax has specific rules for certain foreign passive income of multinational group entities.
What about non-residents?
Non-residents pay non-resident income tax (IRNR) only on Uruguayan-source income, such as rent from an apartment in Uruguay or interest on a local account. To check whether you are a resident, see Uruguay tax residency.
FAQ
Does Uruguay tax worldwide income?
No. It taxes Uruguayan-source income, with the exception of certain foreign investment income of tax residents.
Is remote work for a foreign company taxed in Uruguay?
Yes, if you do it physically from Uruguay: the tax authority treats it as Uruguayan-source income even when the employer is abroad.
Is Uruguay a tax haven?
No. It has a territorial system with incentives for new residents, taxes local income and part of foreign investment income, and exchanges tax information with other countries.
Plan your international taxation
At GlobalTax we analyse the source of your income and your tax residency in Uruguay and at home, in English, Spanish or Portuguese. Contact us.